Guard & Reserve
Put in 5% of drill pay and the government adds up to 5% in free retirement money.
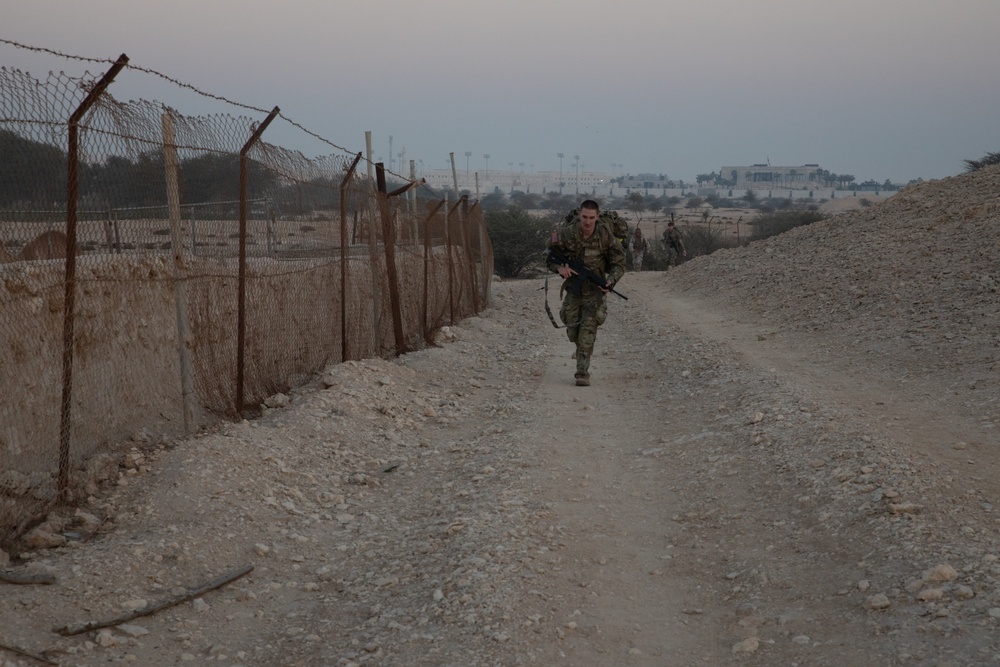
An Army National Guard competitor completes a 15 km ruck march. U.S. Army National Guard photo by Cdt. Ayden Norcross, DVIDS (public domain).
Upload your Leave & Earnings Statement and get a plain-English breakdown of every line.
Open LES Tool→Under the Blended Retirement System (BRS), the government puts money into your Thrift Savings Plan, and that includes drilling Guard and Reserve members. Contribute 5% of your drill pay and the government can add up to 5% on top. Leaving that on the table is leaving free money behind.
BRS gives you an automatic 1% government contribution plus up to 4% in matching, for a total of 5% when you contribute at least 5% yourself. For Guard and Reserve members, this rides on your inactive-duty (drill) pay and your active-duty pay alike.
How the match works
The fine print
Contribute at least 5% of your drill pay. The government 5% is a 100% return before your investments earn a dime.
Source: DoD Blended Retirement and TSP
The 2026 elective deferral limit is 24,500 dollars, up from 23,500 dollars. The catch-up limit at age 50 is 8,000 dollars, and for ages 60 to 63 it is 11,250 dollars.
Those ceilings matter less on drill pay alone, since a full year of drills and annual training for a junior enlisted member runs in the low thousands. They matter a great deal on a mobilization, when your percentage suddenly applies to full active-duty basic pay. See Activation Money.
Source: IRS and TSP Bulletin 25-3
Drill pay is irregular, so check your LES and TSP statements to confirm the match is flowing. Set your contribution as a percentage so it scales with each drill and active-duty period. If you opted into BRS or joined after 2018, confirm your matching clock and election in myPay. Timing is its own problem on the Reserve Component side, covered in Budgeting on Drill Pay.
For most younger members, a low-cost, age-appropriate Lifecycle (L) fund is a simple, diversified default. The point is less about picking funds and more about capturing the full match and letting time and compounding work across a long Guard or Reserve career.
Things to consider
Do reservists really get a TSP match?
Under BRS, yes. The 1% automatic and up to 4% matching apply to drill (inactive-duty) pay and active-duty pay.
When does matching start?
After two years of service for members who entered on or after January 1, 2018. Those who opted into BRS got matching upon opting in.
What if I am not on BRS?
Members under the legacy system who did not opt in do not receive matching contributions. You can still contribute to the TSP.
How much should I contribute?
At least 5% to capture the full government match, and more if you can.
What is the 2026 limit?
24,500 dollars in elective deferrals, with an 8,000 dollar catch-up at age 50 and 11,250 dollars for ages 60 to 63.
Roth or traditional?
Roth TSP can be attractive in low-income years, and traditional lowers your taxable income now. Many members split the difference. A free financial counselor can walk your numbers.
VetraFi does not provide financial, investment, tax, legal, or accounting advice. The content provided is for informational purposes only. You should consult your own advisors before engaging in any transaction.
Earn It.





Comments
Share your experience or ask a question. Comments are reviewed by our team before they appear.
Leave a comment